LOANS & CREDIT
Home Equity & Home Equity Line of Credit (HELOC) Loans
Whether you dream of an epic vacation, college degree, home renovation or more – our powerful equity line gives you the freedom to lock rates whenever you want and keep that rate until the balance is paid. With a low rate that’s there when you need it, you can relax and enjoy the comfort of a sweet home equity loan.
Home Equity or HELOC: Which is right for you?
Equity is the difference between what your home is worth and what you owe on it. A Home Equity Loan and a Home Equity Line of Credit (HELOC) both let you borrow against that equity, but they work differently.
Vanderbilt Credit Union, working in conjunction with Fortera Credit Union, can help you determine which loan type is best for you.
Home Equity: One Amount, Predictable Payments
A Home Equity Loan gives you one lump sum upfront that you repay over a set period. Our Home Equity Loan has a fixed interest rate and fixed monthly loan payments, so you know what to plan for in your budget. You can always make additional payments when the timing is right, and you’ll enjoy zero prepayment penalties for wrapping up your balance a little early.
May be a good fit when: You know how much you need for a specific expense, such as a home improvement project with a set cost.
Home Equity Line of Credit: Borrow as You Go
A HELOC gives you a credit limit you can borrow from as needed during a set borrowing period, called the draw period. You don’t have to use the full amount at once.
Once approved, you have full access to your funds at the ready. You can make withdrawals up to your approved limit whenever you would like (certain fees may apply) and our HELOC even lets you check off multiple items on those bucket and to-do lists together. You’ll have the ability to use up to three rate locks* at one-time. Each lock will have its own rate that is locked in for up to a 10- year term. Once you’ve paid off one of the locks, you can add another in its place. Variable APR* starting at 7.00%1 or 7.50%2.
Stages of a HELOC:
1. Draw Period: (the first 10 years) Use your line of credit while making interest-only payments with the option to pay extra against the principal.
2. Optional Rate Lock: for up to three portions of your balance, you can lock the rate and start making payments. NOTE: Locks are subject to fixed rate pricing which may be lower than your current variable rate.
3. Repayment Period: (the last 20 years), make monthly principal and interest payments to repay the outstanding balance. Note that you won’t be able to draw funds or exercise rate locks from the HELOC during this time.
May be a good fit when: Your expenses will happen over time, such as a renovation completed in stages, or when paying for a child’s college by semester.
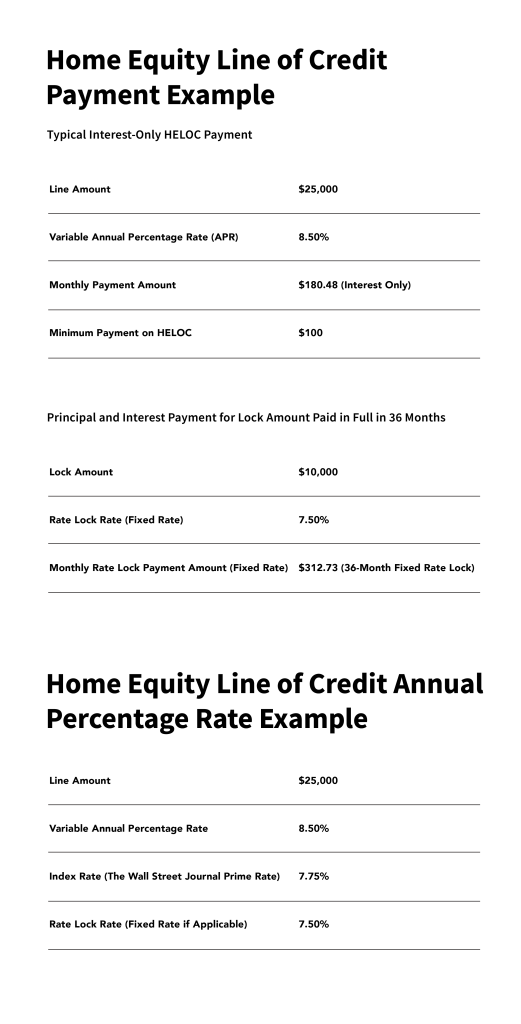
1Interest only Payment Loan to value is less than 80% (7.00%-9.50%APR). 2 Interest Only Payment Loan to Value is greater than 80% (7.50%-8.00%APR) HELOC's adjust monthly on the first day of the month. There is no limit on the amount by which the annual percentage rate can change during any one-year period. The maximum rate is 18.00%. The minimum rate will never be below 3.25%. *APR=Annual Percentage Rate. The ANNUAL PERCENTAGE RATE you receive will be based on credit worthiness and loan to value amount. Not all members will qualify for the best or lowest rate. All loans are subject to approval. Rates, terms, and conditions are subject to change.
Auto-pay Advantage: A discount of 0.25% will be deducted from the above stated annual percentage rates when the payment is received automatically from a Fortera draft account. This discount is only available on new loan transactions with an effective date on or after the date of this addendum. The annual percentage rate will default back to the normal rate in the event the payment status or draft account status changes.
**Loan to Value Ratio (LTV): A ratio used by lenders to calculate the loan amount requested as a percentage of the value of a home. To determine the loan to value ratio, divide the loan amount by the home's value. The LTV ratio is used to determine what loan types the borrower qualifies for as well as the cost and fees associated with obtaining the loan.